PROPERTY FINANCE FROM

5.0% P.A.

Minimum Amount $5.0 Million

Latest News

The Long View, August 2026 – Finance Intelligence Newsletter

Written by Michael Long

The August edition of The Long View is attached — here’s what’s inside: 

Inflation overshot the RBNZ’s own forecast — annual CPI printed 4.1% for the June quarter on 21 July, not the 3.9% the Bank had pencilled in.

The labour market is the counterweight — unemployment hit 5.6% in the June quarter, the highest since March 2014, and 6.0% in the North Island against 3.7% in the South.

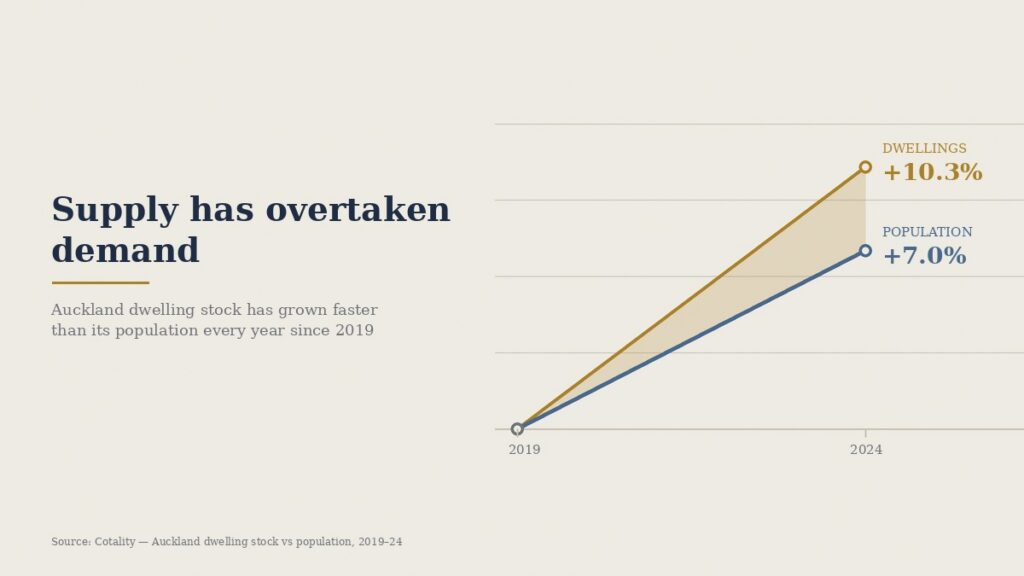
Supply has overtaken demand, and it is now in the prices — 13.1% of Q2 resales sold below what the owner paid, the highest since 2012; roughly 20% of townhouses and 41% of apartments. Consents are still running +19% against net migration of just 17,600, well under the 31,200 long-run average.

The full data — rates tables, Auckland and Christchurch market breakdowns, building consents, Rental, Stressed sales, Supply&Demand, Migration — are all in the newsletter.

As always, if any of it prompts a question about your project or funding position, I’m a phone call away.

The Long View, July 2026 – Finance Intelligence Newsletter

Written by Michael Long


The July edition of The Long View is attached — here’s what’s inside:


RBNZ delivered the flagged hike. OCR up 25 bps to 2.50% on 8 July, unanimous after May’s 3–3 split. All four major banks lifted floating rates +25 bps within days; next MPS isn’t until 2 September, but economists now see 2-3 more hikes coming.

The Hormuz truce collapsed the same day — Brent has surged from ~$72 to $88.10 in ten days. Fuel and steel repricing risk is back for H2 — fix-price contracts remain essential.

Building consents confirmed a genuine rebound. 39,737 dwellings consented in the year to May (+19%), Auckland +22% and Canterbury +30% the biggest movers.

Non-bank lenders sit outside the RBNZ’s new bank-only DTI limits — a genuine structural edge for development finance, alongside the FMA’s 1 July takeover of consumer credit regulation.


The full data — rates tables, Auckland and Christchurch market breakdowns, building consents, Economist Watch, Migration — are all in the newsletter.


As always, if any of it prompts a question about your project or funding position, I’m a phone call away.
The Long View, June 2026 – Finance Intelligence Newsletter

Written by Michael Long


The June edition of The Long View is attached — here’s what’s inside:


The OCR held, but only just. The 27 May MPS delivered a 3–3 split vote — the most hawkish hold on record. Governor Breman’s casting vote kept rates at 2.25%, but the market is now pricing a 75% probability of a hike on 9 July. If you have development or construction funding to arrange, the window to lock in current rates is narrowing.

The Strait of Hormuz is reopening — a US-Iran MOU was signed on 14 June — but recovery is slow, with 600 ships backlogged and diesel and steel costs still elevated through H2. Fix-price build contracts remain essential for any project breaking ground this year.

Stressed sales are at a record. Mortgagee listings hit 109 per quarter — the highest since tracking began — and distressed stock is selling at around 19% below market value. For well-capitalised developers and investors, this is a real opportunity, if you move with the right advice.

Budget 2026 delivered a $400M consent incentive — councils now earn more the more they consent. Fast-consent markets like Christchurch, Selwyn and Tauranga are the immediate beneficiaries.

The Long View, May 2026 – Finance Intelligence Newsletter

I’ve just launched The Long View — a monthly finance intelligence newsletter I put together for developers and builders in the NZ market. It covers interest rates, construction costs, consent data and market snapshots for Auckland and Christchurch, with a Developer’s Tip each month. Thought you’d find it a useful read given what you’re working on.

If there’s ever anything I can help with on the finance side — whether it’s a new deal, refinancing, or just a second opinion on structure — feel free to give me a call. Always happy to have a chat.

Michael Long